Search
  • 30+
    Power generation and
    infrastructure transactions
    completed in the last five years
  • 10+
    Mandates currently in market
    across the power value chain
  • 20+
    Energy and digital infrastructure
    transactions in the last five years
  • Design, power solutions & equipment

    OEMs and component manufacturers, precision machining, engineering and design consultancies, power solutions and distributed generation.

  • EPC & electrical construction

    Engineering, procurement and construction, electrical and mechanical contracting, grid and substation delivery, data centre fit-out and technical integration.

  • Operations & maintenance

    Long-term O&M contracts across thermal and renewable fleets, asset management, inspection, testing and compliance services.

  • Maintenance, repair & overhaul

    Rotating equipment MRO, component repair and coatings, generator and reciprocating engine services, independent and multi-OEM service providers.

  • Upgrades & life extension

    Uprates and efficiency retrofits, controls modernisation, emissions and flexibility upgrades, life-extension programmes for the installed base.

  • Gas, thermal and nuclear
  • Hydro, wind and solar
  • Energy transition: BESS, bioenergy, waste-to-energy
  • Rotating equipment and turbine services
  • Grid equipment and electrical products
  • Transmission and distribution EPC
  • Substations, interconnection and metering
  • Grid maintenance and vegetation management
  • Data centres, fibre and towers
  • Backup and distributed power systems
  • Electrical contracting and infrastructure integration
  • Industrial and process end-users

What clients get from a practice built around the whole chain

  • Whole-chain coverage

    We cover equipment, engineering, construction and services as one connected market — so we can position a business against every credible pool of buyers, not just its closest peers.

  • Buyer-led positioning

    We translate installed-base access, backlog quality, technical accreditation and field workforce into the investment case that acquirers in this sector actually underwrite.

  • Valuation perspective

    Continuous transaction activity and proprietary valuation data give an informed view of where strategic and sponsor value sits across each sub-sector.

  • Strategic relationships

    Active dialogue with 5,900 corporates and 2,000 private equity funds firm-wide, including the OEMs, service platforms and infrastructure investors most active in power.

  • Cross-border reach

    19 offices across the Americas, Europe, Asia and the Middle East, with local teams running cross-border processes for European, US and Latin American assets.

  • Senior-led execution

    Senior bankers stay on the deal from preparation and buyer engagement through diligence, negotiation and completion.

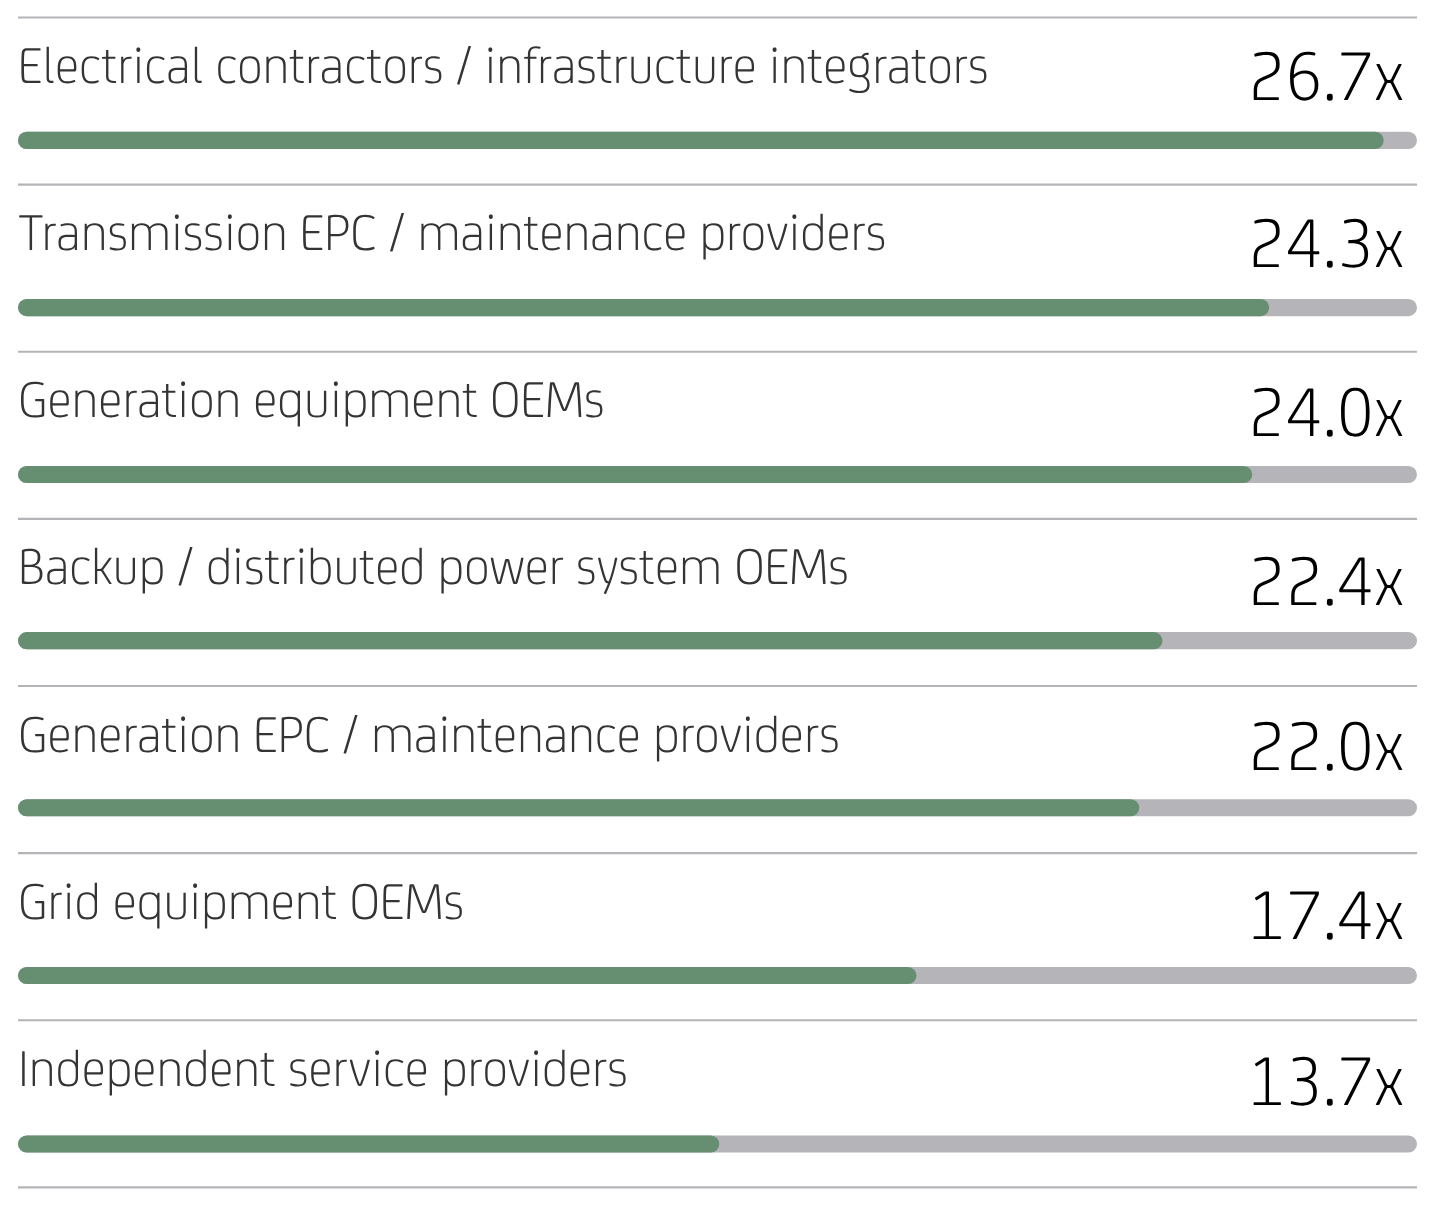
EV / NTM EBITDA. Source: company filings, Capital IQ, Mergermarket, consensus estimates as of 21 May 2026.

Public comparables and precedent transactions are at or near peak levels

8.0x–15.0x is Alantra’s estimate of strategic value for private businesses across the power generation, transmission and consumption chain, depending on margin profile, scale and capability, informed by precedent transactions advised by Alantra and other industry transactions with disclosed economics.

Equipment manufacturers currently command a premium to service providers, supported by demand for critical equipment, supply chain constraints and long-lead order backlogs. Service providers closest to end-market demand — electrical contracting and data centre delivery — are trading at the top of their historical range.
A track record spanning founder-owned businesses, sponsor-backed platforms and corporate carve-outs